Maybank vs Public Bank for a Gran Max Loan: Variable vs Fixed Reducing Rate Explained
Published: 27 October 2026·Last updated: 27 October 2026
Maybank 3.2% variable or Public Bank 3.5% to 3.9% fixed? Compare eligibility, rate type and repayments for a Daihatsu Gran Max company loan.
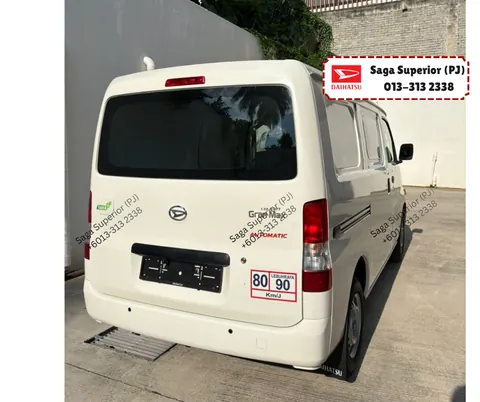
Maybank offers 3.2% on a variable reducing rate to companies registered with SSM for more than 3 years. Public Bank offers 3.5% to 3.9% on a fixed reducing rate and is easier to get approved. On a RM70,639 loan over 7 years, the monthly gap is only about RM9 to RM22, so approval and rate certainty usually matter more than the headline rate. Rates are as of 21 Oct 2026 and subject to bank approval.
Side by side
| Maybank | Public Bank | |
|---|---|---|
| Rate | 3.2% | 3.5% to 3.9% |
| Rate type | Variable, reducing | Fixed, reducing |
| Who it suits | Companies registered with SSM for more than 3 years | Easier approval, including companies under 3 years |
| Monthly payment (RM70,639, 7 years) | About RM940 | About RM949 (3.5%) to RM962 (3.9%) |
| Total interest over 7 years | About RM8,300 | About RM9,100 to RM10,200 |
The loan amount is the Gran Max Panel Van MT at RM78,488 with 10% down. Repayments are our own calculations for illustration.
What 'reducing rate' means
Both banks charge a reducing rate: interest is calculated on the balance you still owe, which falls with every payment. That makes a reducing rate cheaper than a flat rate with the same percentage, so the two quotes above can be compared directly with each other.
Fixed vs variable
Fixed rate (Public Bank). The rate stays the same for the whole loan, so your payment is predictable. You will not benefit if market rates fall, and the rate you are offered can sit anywhere in the 3.5% to 3.9% range.
Variable rate (Maybank). The rate can change during the loan, so what you pay can go up or down. How a change is applied depends on your loan agreement, so ask the bank whether it changes your monthly payment, your tenure or both.
Here is an illustration on the same RM70,639 loan at Maybank's 3.2%. Suppose the rate rises by 1 percentage point to 4.2% after two years:
| Scenario | Monthly payment (about) |
|---|---|
| Years 1 to 2 at 3.2% | RM940 |
| Years 3 to 7 if the rate rises to 4.2% | RM963 |
| Years 3 to 7 if the rate falls to 2.2% | RM917 |
In the higher-rate case, total repayment is about RM80,300. That is still slightly below a fixed 3.9% loan (about RM80,800) and above a fixed 3.5% loan (about RM79,700). The cost difference is small either way; what changes is how certain your budget is.
How to choose
- Company registered for more than 3 years and comfortable with payments that may move: Maybank has the lowest rate.
- Company registered for less than 3 years: Public Bank is the practical option, because Maybank does not accept these applications.
- Thin margins or a fixed monthly budget: a fixed rate gives certainty even if it costs a little more.
- Not sure: tell us your company's SSM registration date and we will recommend which bank to apply to first.
We also work with Affin Bank and Hong Leong Bank, and offer credit through Yulon Capital. Ask us for current offers. All applications need the director's NRIC and driving licence, the company's SSM registration documents and its latest 6 months of company bank statements.
This article is general information, not financial advice. Final approval, rate, margin and tenure are decided by the bank.
FAQ
Is Maybank cheaper than Public Bank? Its rate is lower (3.2% against 3.5% to 3.9%) but variable. Over 7 years on RM70,639, interest differs by roughly RM800 to RM1,900.
Can a company under 3 years old get the Maybank rate? No. Maybank needs SSM registration of over 3 years, so we recommend Public Bank.
Will my monthly payment change with a variable rate? It can. Ask the bank how rate changes are applied under your agreement.
Can I choose a different bank? Yes. We also work with Affin Bank and Hong Leong Bank. Ask us.
See also our guide to Gran Max financing and the loan calculator.